
What do cookies, protein shakes and high-end luxury consumer brand items all have in common?
Other than being fun and unique products to “Add To Cart” during an online or in-person shopping jaunt, they also represent a small component of the $8.3 trillion1 of annual personal consumer expenditure in retail trade and restaurants that presents a massive opportunity for consumer-focused private equity investors. At 30% of US GDP2 and 45% of personal consumption expenditure3, this slice of the economy covers food & beverage, consumer brands, restaurant and retailer activity within the United States.
Take for instance, the “consumer brand investing success story”4 that is Tate’s Bake Shop, a well-known gourmet cookie brand that is widely available at Publix and Costco. As part of their methodical research surrounding evolving consumer tastes, Riverside honed in on the shifting consumer preference for all-natural and gourmet dessert options5. Riverside gave Tate’s the resources they needed to expand and enhanced Tate’s distribution, production, and manufacturing efficiency.4
Riverside fostered Tate’s strong relationships with retailers – enabling Tate’s to understand changing customer needs and preferences – and develop unique products like snack-sized “Tiny Tate’s” and on-trend flavors like Ginger Zinger and Coconut Crisps. Riverside also enabled Tate’s to be able to meet this demand through cultivating strong relationships with Tate’s distributors. Tate’s was sold to Mondelez International (an international food conglomerate) for $500MM,4 a great outcome for Riverside’s investors and for Kathleen King who first opened the roadside cookie stand.6
Within this opportunity set, private equity investors conduct significant research surrounding changing consumer preferences and deploy capital in companies which are poised to capitalize on one or many of these consumer trends at various sizes and stages. Private equity investors take a “treasure-hunt” approach, sometimes honing in on a small upstart at the intersection of multiple compelling themes or finding a highly recognizable brand with deep customer affinity and empowering them to grow in new sectors through expansion capital and strategic oversight. At each stage of a consumer-focused company, private equity aims to bring operational improvements, industry insights, and best-in-class partnerships to the table.
In addition to demand for all-natural and gourmet dessert options, consumer preferences highlight an increased focus on wellness. Only What You Need (OWYN), a plant-based protein beverage, was founded by two former professional athletes in 2017.8 Catering to a health and wellness focused demographic, OWYN’s ready-to-drink protein shake excludes sugars, syrups, and saturated fats,9 as well as the top eightallergens.9 Initially launched via e-commerce, OWYN received patient capital and strategic guidance from Purchase Capital in 2022.10 OWYN continues to experience double-digit revenue growth and is expected to have $120MM of net sales in 2024.10 OWYN now outsells legacy brands like Muscle Milk and is carried in Kroger, Target, Publix and Whole Foods nationwide. It was recently acquired by Simply Good Foods, a developer, marketer and seller of branded nutritional foods, for $280MM in cash.11
The wellness trend has also expanded to beauty, where it accounted for an extra $46B or 30% of market value to the overarching US beauty sector, which presently stands at $148B.12 Beauty is a small component of the overarching consumer brand sector, which includes clothing, footwear, pets and more. Clothing and footwear alone represented $1.4T of economic activity within 2023.7 Within the consumer brand sector, luxury brands have outperformed market indices, while non-luxury brands have lagged – which has increased caution amongst investors for the non-luxury category.13 This rings true within beauty as well, with North American luxury beauty sales growing 15% in 2023.12
All of these metrics highlight how highly recognized brands with deep affinity amongst their customer base have been able to pass along cost and price increases to consumers, without suffering a dip in demand, relative to less differentiated counterparts. Unlike their commoditized counterparts, unique consumer brands capitalizing on key consumer themes and trends require a well-developed network of relationships to source, as well as deep understanding of the sector to implement operational improvements and long-standing partnerships.
Despite a slowdown in consumer M&A activity in recent quarters due to softened consumer sentiment from rising rates, KPMG projects that 2024 consumer-focused M&A is set for an upswing. Private equity investor confidence in the consumer sector has increased, driven by the first of many forecasted rate cuts from the European Central Bank and other global central banks, larger deals and rising IPO activity.12
At approximately $18.6 trillion14 and representing nearly 68% of the U.S. GDP, consumption is the primary driver of the U.S. economy and presents a massive opportunity for attractive growth investments. Real* personal consumption expenditure experienced an average 3% year-on-year growth rate over the last decade.15 Investors would do well to consider dedicated consumer allocations within a diversified portfolio, as missing out on a large and steadily growing slice of the economy might prove costly over the coming years.
*Real personal consumption expenditure is adjusted for inflation
Sources
Independent investment advisors venturing into the domain of private funds must consider an array of structural considerations.
Setting up a private fund necessitates creating appropriate legal entities. Commonly, private funds opt for structures like limited partnerships (LPs) or limited liability companies (LLCs). In an LP, for instance, there must be a general partner who manages the fund, while investors come on board as limited partners.
The formal documentation that delineates the relationship between the fund managers and investors is critical to the fund’s operation. For a limited partnership, this is typically encapsulated in a Limited Partnership Agreement (LPA), which outlines vital legal terms such as capital calls, profit distribution, management fees, and terms concerning the withdrawal of limited partners. These documents ensure that all parties are clear about their roles, responsibilities, and benefits.
A private fund usually operates alongside a distinct investment advisor entity that furnishes investment advice. This entity, as well as any other management bodies associated with the fund, must be separately constituted. Each of these entities will have its own legal structure and accompanying contractual agreements that govern their operations.
Raising capital is a nuanced aspect of fund management that requires careful consideration of the investment focus—such as the types of assets and the geographical emphasis of investments—and leveraging the credentials and track records of the founders. Fundraising must adhere to federal and state securities laws, typically under exemptions such as Rule 506(b) and Rule 506(c) of Regulation D, which allow for raising capital without the need for registration under the Securities Act.
These are just a few of the structural considerations when it comes to setting up a private fund.
Gridline provides the quickest and most seamless solution for launching an institutional-quality fund. It manages all the aspects covered above, from legal and fund formation through capital raising and reporting over the vehicle’s life, while providing an exceptionally high degree of visibility into fundraising, investment performance, and cash flows.
The allure of private equity lies in its potential for superior returns, which hasn’t escaped individual investors’ notice. Over the past quarter-century, private equity has yielded an impressive 14% return globally, doubling the 7% offered by the MSCI World Index.
Nevertheless, in contrast to public markets, success in private markets is far from a given, owing to the challenge of picking the right investments and the relative scarcity of data.
Mechanism design is employed to safeguard returns on private investments, including but not limited to governance, project finance, return protection, and meticulous control mechanisms.
Mechanism design, often hailed as ‘reverse game theory,’ has its roots firmly planted in the arena of economic theory. Championed by Leonid Hurwicz, the 2007 Nobel Laureate in Economics, it revolves around creating a strategic environment or ‘game’ that induces participants to behave in a way that leads to a desired outcome.
Hurwicz and his collaborators, Eric Maskin and Roger Myerson, also Nobel Laureates, made significant contributions to developing and applying this theory. Their work has provided a theoretical basis for understanding how private markets function.
As per Hurwicz’s theory, mechanism design attempts to construct systems that provide the right incentives to encourage the most beneficial behavior from each participant. It’s like designing a game where the rules are laid out so that the players, acting in their own self-interest, will bring about an optimal outcome for everyone involved.
In private markets, the mechanism design theory finds significant application. Consider private equity, for example, where the relationship between general partners (GPs) and limited partners (LPs) is a prime case of a ‘game.’ The GPs, who manage the investments, and the LPs, who provide the capital, have incentives and information. The mechanisms used, such as carried interest and hurdle rates, align the interests of the GPs and LPs, leading to mutually beneficial outcomes.
Fortunately, private market conventions have evolved to align interests. For example, fees over the first several years of an investment partnership are commonly calculated on committed capital rather than invested capital, reducing the incentive for GPs to quickly invest in substandard deals to start receiving fee income. Similarly, carried interest (commonly called carry) often represents 20% of the proceeds from any investment sale, but that is frequently only available to GPs if the investment being sold has compounded in value above 8% annually. This ensures that GPs are not being rewarded for holding a mediocre investment for several years, nor are they receiving carry based on their own estimates of portfolio value.
A deep dive into the performance of private markets over the past two decades unveils a consistent trend of outperformance compared to their public counterparts. The Hamilton Lane 2022 market overview report provides compelling evidence of this. It reveals that every year in the past twenty, buyout returns in private markets have surpassed the MSCI World PME by a staggering average of 1,000 basis points.
Similarly, private credit has not lagged, having consistently exceeded the performance of leveraged loans annually by an impressive 625 basis points over the same period. This long-standing trend demonstrates the potential for superior returns in the private market sector.
During 2022, private markets displayed remarkable resilience, surpassing public strategies across all sectors. Illustratively, buyout returns in private markets outpaced the S&P 500 by almost 2,050 basis points. Furthermore, the private sector’s infrastructure and real estate exceeded the FTSE All Equity REITs Index by a considerable margin, over 3,400 basis points, to be precise.
A 2023 survey showed that 86% of participants believe that the trend of private markets outperforming public markets is likely to continue. This sentiment points to the growing confidence in private markets and their potential for higher returns.
Moreover, historical data indicates that private equity provides superior risk-adjusted returns and tends to outperform public equity by a more significant margin, especially during periods of economic distress. This pattern suggests that the mechanisms at play within private markets can effectively contribute to higher returns.
With Gridline, private market investing becomes more straightforward and more accessible. We provide the tools to navigate these markets effectively, harnessing the power of diversified, professionally managed funds.
When IBM chairman Thomas Watson was selected to serve as ambassador to the USSR in 1979, he had a problem. Ethics norms of the time dictated he needed to dispose of his personal stakes in several VC funds he’d accumulated over years of investing in the early computing industry. Watson tapped Dayton Carr to help market the fund interests. After significant effort, Carr was able to find willing buyers in the nascent private markets ecosystem to complete the sales. This convinced Carr to set up the world’s first dedicated secondaries firm, Venture Capital Fund of America, to pursue the strategy full-time.1 Carr ended up nurturing several industry luminaries, including Jeremy Coller (CEO of Coller Capital) and Andrew Isnard (CEO of Arcis Group).
Today, the industry Carr helped birth transacted $112B of volume in 2023 and has spread into every private asset class.2 Whether because of competitive returns, diversification, or quicker cash conversion cycles, secondaries have become an increasingly important arrow in the quiver of private market allocations available to investors. This article will walk through two common types of secondaries deals, recent trends in different corners of the market, and things for investors to keep in mind before jumping in.
Watson’s quandary is an example of the original form of secondaries transactions, LP stake sales. These involve Limited Partners (LPs) looking to sell private fund interests and secondaries managers hoping to acquire them for less than their intrinsic value. LPs might be looking to sell because of shifting strategic mandates, idiosyncratic personal factors, loss of conviction in a manager’s strategy, or to free up liquidity. Buyers are tempted by typical discounts to Net Asset Value (NAV) at purchase, a shorter runway to liquidity as typical sales take place in the latter years of a fund’s life, and a mostly known and well-diversified portfolio.
Many private fund contracts require General Partner (GP) consent before interests are transferred, which means the GP must approve LP stake purchasers before any sale. This is especially true for Venture managers, who can be sensitive about allowing new investors into the partnership who might publicize portfolio company information. These dynamics help existing LPs in a fund get a leg up when purchasing stakes, as they can be trusted not to circulate information and are knowledgeable enough about the portfolios to ascertain their true value. Because that pool of LPs is often smaller than buyout funds, bidding for venture portfolios tends to be less competitive.
As secondary markets developed, a pattern of LPs looking to unload interests in long-dated funds emerged. Because fund interests might be a bit small by that stage of a fund’s life, LPs might not get great asset pricing. GPs became aware of this dynamic and introduced continuation funds, where LPs would be given the option to sell their interests in one large block and hopefully fetch a better price. GPs are quite enthusiastic about the prospect as it allows them to reap significant carry when LPs extinguish their fund interests and restart the clock on fee income (which GPs receive from new purchasers in exchange for continued management of the assets). Less cynically, they can also allow GPs to pursue more long-term value enhancement plans rather than forcing assets to market prematurely.
From a purchaser’s perspective, continuation vehicles offer the chance to purchase significant exposure to a concentrated portfolio. Because managers typically run a bidding process for the right to participate, secondaries purchasers can get an opportunity to learn more about the assets they’re purchasing, particularly if they are less familiar with the manager. In the words of one market participant, “Managers can sell these assets to any number of people.”3 This same broadly marketed process usually means more competitive pricing, requiring purchasers to be spot on when forecasting portfolio company growth.
Whether on the LP or GP side, this market environment has been conducive to significant secondaries volume. Jefferies estimates that 2023 was secondaries’ second-largest year behind 2021, with volume fairly evenly split between GP continuation vehicles and LP stake sales.2 LP volume was dominated by Pensions and Sovereign Wealth Funds, which is perhaps unsurprising as they are the largest individual pools of capital. On the GP side, higher rates made the traditional exit routes of IPOs, M&A, and dividend recaps scarce, creating a strong opportunity for continuation funds to provide liquidity. Continuation funds reached an all-time high of 12% of global sponsor-backed exits, more than double the average for the previous 3 years.2
The thirst for liquidity has had a knock-on effect on pricing. Below, you’ll find a graph of annual pricing on LP deals across asset classes, where eagle-eyed readers will note that every asset class priced below its pre-COVID average in 2023. However, this was far from evenly distributed as buyout deals rebounded to 91% of NAV while venture pricing remained depressed at 68% of NAV. Part of this spread is due to differences in valuation policies, as buyout managers are often slower to write up portfolio companies than VCs, who typically write up portfolio companies every 1-3 years as they raise additional rounds of capital.4 Those external VC rounds are usually a strong anchoring point for venture valuations, which means that venture managers are slower to write down the value of their portfolios in a downturn.
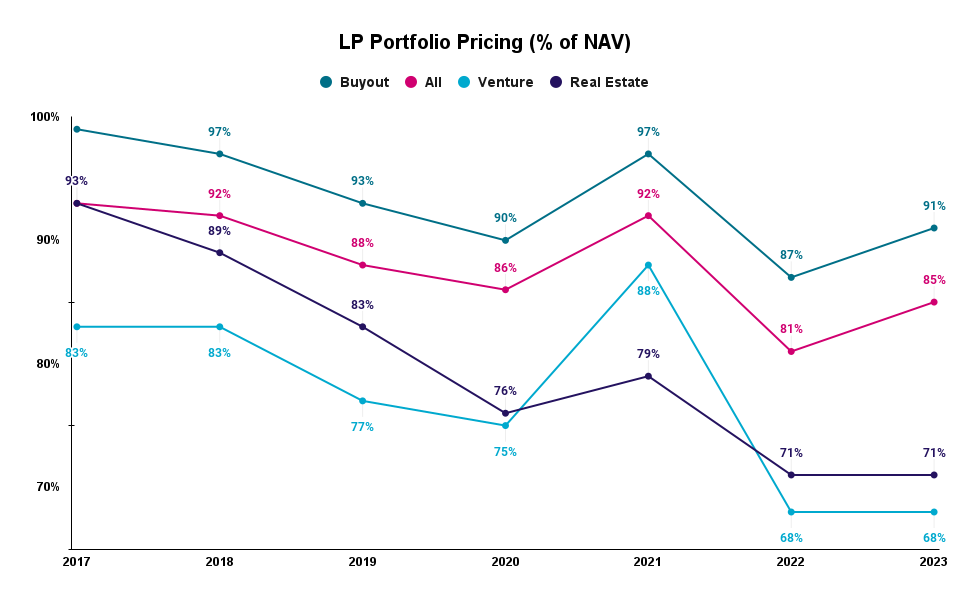
Beyond technical pricing differences is a supply and demand mismatch. Jeffries pegs the dedicated capital available to pursue secondaries at an all-time high of $255B or 2.3x the market’s volume.2 Most of this dry powder has been raised to pursue buyout opportunities, including $23B for Lexington Partners’ latest fund5 and $25B for Blackstone’s most recent vintage.6 By contrast, the closed nature of many venture secondaries opportunities, smaller opportunity sets, and the higher bar on the diligence of rapidly changing venture-backed companies makes it more difficult to deploy capital at scale. This shows up in the fundraising figures, with the largest secondaries fundraises dedicated to venture Industry’s recent $1.7B vintage7 or StepStone’s $2.6B 2021 close.8
Finally, investors should consider how private secondaries compare with public markets. In the past year, the S&P 500 is up 28%, and the NASDAQ-100 is up 50%.9 Cambridge Associates’ most recent one-year buyout performance was pegged at 6.4%, while venture turned in a -10.4% return.10 So while private company valuations might have looked stretched relative to their public peers in 2023, the growth of public comps mainly fueled by multiple expansion makes the concern less salient in 2024.11
There is strong evidence that more niche secondaries managers engaging in less competitive bidding processes can produce outsized returns. Phil Huber at Cliffwater recently put out a note that segments the secondaries landscape into generalist firms with larger fund sizes and broader remits and specialist firms focusing on a narrower slice of the market.12 He found that Specialists outperformed by ~5% per year across a 250 fund dataset. This makes sense, as we would expect excess returns to be eroded in markets with more dry powder outstanding.
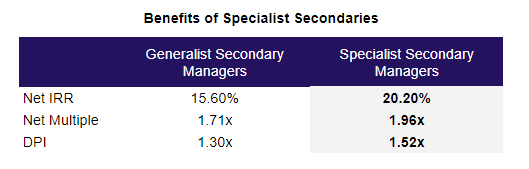
Bringing it all together, investors can benefit significantly from secondaries funds due to a faster payback period than primary investments, increased diversification, and competitive returns. Now is a particularly advantageous time to tap the secondaries markets with discounts to NAV above pre-COVID averages across asset classes and even further above average in more niche spaces like venture. Higher prices for public stocks make these entry points more valuable on a relative basis. When considering how to play the space, investors should consider the degree to which specialization gives a manager they are considering partnering with a relative advantage.
Investors and their advisors typically apply a set of common sense principles to craft a balanced public market portfolio that performs over the long term. Several of these same principles are essential when investing in private markets and can be applied when investing through Gridline.
Trying to beat the market tends not to work. This is why savvy investors typically do not just buy Apple and Microsoft when they could own the entire Nasdaq.
Historically, most people who say “I’m in alts” are participating in a couple of funds but don’t have a private market portfolio built on proven principles.
Rather than trying to hit a home run with one or two funds, Gridline’s thematic portfolios allow investors to spread capital amongst multiple managers, multiple underlying sectors, more geographies, and more vintages.
Even if the portfolio were to simply track the private equity market and deliver a median return, for example, an investment in this type of product still boosts the blended average return of an investor’s entire portfolio. Layer on a very large sourcing funnel and rigorous due diligence, and the portfolio’s total results have the opportunity to outperform industry benchmarks.
The core-satellite approach deployed by Gridline has been utilized in the public space for decades. Investors have beta generators, often at least 40-50% of their public market portfolios, which track the asset class, and potential alpha generators, which can deliver superior returns.
Just as in public markets, in private markets, academic research supports the addition of emerging private market fund managers and their ability to generate significant alpha.
In public markets, investors often make regularly timed purchases in the asset class to smooth out volatility rather than throwing in a lump sum.
The same applies to the private markets. For example, if investors want PE exposure, they can participate in our Buyout Portfolio in the 2024 vintage, 2025, and 2026 to get steady exposure to the asset class throughout changing economic conditions.
By introducing index-based investing, Vanguard became one of the largest and most influential forces in the asset management industry. It offered investors a low-cost way to instantly buy a diversified segment of the public markets.
Gridline provides this same ability within the private markets. Gridline’s thematic portfolio funds are multi-fund products designed to provide diversified exposure to a particular asset class or strategy with a single investment and low fees.
Funds are carefully selected to include complementary strategies capable of mitigating risk and enhancing return expectations, ultimately providing investors with high-quality, low-cost private market diversification.
Similar to how a buyout manager would provide capital and expertise to a portfolio company in exchange for equity in the business, GP Stakes investors provide capital and expertise to General Partners (GPs) in exchange for a minority stake in the underlying management company and its GP entities (their funds). The GP Stakes Investor receives a share of future cash flow from net management fee revenue and profits, incentive fees, GP co-investments, and balance sheet realizations. GPs use the capital to help grow the firm by meeting co-investment requirements for upcoming funds, succession planning, or developing new strategies.
There are some unique aspects to GP Stakes investing that set it apart from other private equity strategies:
Ultimately, the investors in this strategy are rewarded when GPs and their funds perform well – raising larger funds, returning to market sooner, achieving better results, and charging higher fees. If you want to learn more about the ins and outs of GP Stakes investing, read our blog post on the topic.
Gridline enables you to invest with top-tier fund managers across private credit, venture capital, private equity, and real assets. Book a time to speak with a member of our team to learn more, or sign up in minutes by clicking the button below to gain access to the platform.
Liquidity is the ability to convert an asset into cash quickly and without a substantial discount. In other words, it’s how easy it is to sell an asset. Stock markets like the New York Stock Exchange are considered highly liquid because the shares of most publicly traded companies can be bought or sold rapidly and at close to their true value.
With hundreds of billions of dollars in daily trading volume, NYSE’s buyers and sellers can be sure to find each other and complete transactions quickly. Private markets, on the other hand, are much less liquid.
Private market investments often come with a “lock-up” period, meaning that investors are unable to sell their shares for a certain amount of time. While venture funds can have a hold period of up to ten years, disbursements can begin as early as year five or six, with VC-backed companies going public on average 5.3 years after securing their first investment.
This lack of liquidity can be frustrating for investors who want to cash out their investments sooner. But it’s important to remember that illiquidity is often the price of admission for higher returns.
The illiquidity premium is the higher return investors expect to earn for an illiquid asset. This risk premium compensates investors for the inconvenience and added risk of being unable to sell their investment quickly if needed.
For example, let’s say you invest $1,000 in a stock that pays a 5 percent annual dividend. After one year, you’ll have earned $50 in dividends, making your investment worth $1,050.
Now, let’s say you invest the same $1,000 in a private company that doesn’t pay dividends but is expected to go public in five years. Suppose the company’s IPO is highly successful, and you sell your shares for $2,000, earning a 100 percent return on your investment.
However, there’s also a chance that the company might not go public or that its shares will be worth less than you paid when it finally lists on an exchange. So, there’s more risk involved in this investment than there was with the stock that paid dividends.
To compensate you for this additional risk, venture capitalists typically expect to earn a higher return on their investments than they would from stocks or other kinds of investments.
Despite the common perception that private markets are illiquid, some recent changes have made it easier for investors to cash out their investments sooner.
One of the most notable developments is the rise of secondary markets, which provide a way for investors to sell their shares in private companies before they go public. According to a report by Common Fund, secondary transaction volume in the first half of 2021 increased to $48 billion, compared to the first half of 2020 volume of $18 billion. This trend is likely to continue as more and more investors look for ways to cash out of their illiquid investments sooner.
Private market liquidity is often misunderstood. While it’s true that these investments can be less liquid than stocks or other kinds of assets, there are some recent developments that are making it easier for investors to cash out sooner. And, despite the added risk, these investments can still offer attractive returns.
In 1969, a team of researchers at UCLA sent the first message between two computers to Stanford on the Advanced Research Projects Agency Network (ARPANET). Often known as the forerunner of the internet, ARPANET was funded by the Department of Defense to link research institutions with government grants to speed technological development. It only took a few years for one of the academics, Bob Thomas, to create a program named Creeper that could track network activity and report back its findings. This was quickly followed by Ray Tomlinson’s Reaper antivirus software, which chased and deleted Creeper wherever it was found.
This tit-for-tat between Bob and Ray is the first example of cybersecurity in action, and for the past five decades, the battle between those looking to penetrate online networks and those erecting defenses has continued to escalate. In 2023, end-user spending in the market for information security from cyber attacks was projected to reach $188B, which would represent 11.3% growth from 2022. Estimates for how large this market can get vary widely, but a study by McKinsey pegged the top end at $2 trillion.
Why does such explosive growth appear likely? One way to approach that question is to consider how much cybercrime costs today and how that’s likely to change. The team at Cybersecurity Ventures estimated that cybercrime would cost $8 trillion in 2023 and $10 trillion by 2025 due to a host of costs, including data destruction, stolen money, IP theft, and reputational harm, among others. Another barometer includes surveys of top executives purchasing cyber defenses as they are the ones writing the checks. Morgan Stanley asked 100 Chief Information Officers in early 2023 about which programs would receive the largest spending increase, and Security Software came first.1 More revealingly, when asked which programs are most likely to be cut, none of the CIOs mentioned Security Software.
Not only is explosive growth possible, but there are reasons to believe startups will have an outsized role to play in defending against the next generation of attackers. One is that entrepreneurs can structure their firms to prevent today’s threats. Cyber professionals have already started to see Generative Artificial Intelligence (AI) contribute to cyber attacks by making it cheaper for groups to run spear phishing or automated customer support scams. The US government has noticed, setting up an AI Security Center within the National Security Agency (NSA) to guard sensitive information that can’t always be addressed with third-party software. Similarly, advances in quantum computing threaten to make many current encryption methods obsolete. Companies built to stop these new vectors of attack stand to benefit if they can outperform legacy players, and historically, incumbents have struggled to innovate on new products while staying at the cutting edge of their existing products. This is especially easy because experienced cyber operators can offer consulting services independently to generate revenue while developing the next software program to productize their insights.
Considering the size and growth of the cyber market, you might expect the venture industry to be rushing headlong into cyber. TechCrunch’s data disagrees, and they estimate Security startups only raised $2.7B in funding over the first quarter of 2023, down 58% year over year. Beyond a general funding malaise, VCs also might be reacting to the difficulties in investing in the space as a generalist. Cyber-specific VCs enjoy advantages on the sourcing side because their relationships with executives purchasing cyber solutions can help startups get a foot in the door with potentially huge clients. They are also advantaged with investment diligence because extensive experience allows them to more easily separate overhyped players from true security breakthroughs. This is crucially important in an industry where companies can grow revenue before the flaws in their security solutions manifest.
Cybersecurity is an industry ripe for continued growth and disruptive innovation. As investors consider how they want to position portfolios against potential disruptions from AI or quantum computing, it would be wise to consider how cybersecurity investments could function as an (imperfect) hedge. We are excited to see how the space develops in the years ahead and hope that those building protective walls outpace bad actors seeking to scale them.
Over the course of this year, we’ve added a variety of new features to the Gridline platform as we continue on our mission to add efficiency and transparency to private market investing. Here are just a few of our favorites:
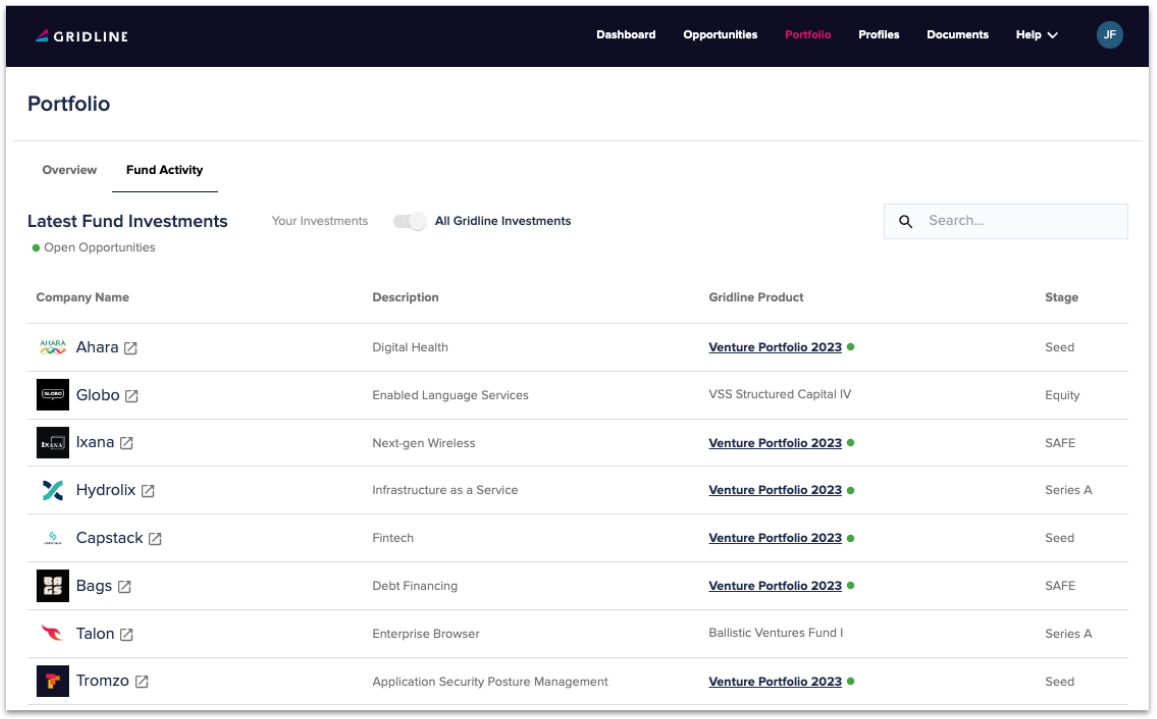
See all of the individual companies that your dollars are invested in. Haven’t invested yet? You can still see all portfolio companies across the funds currently and previously available on the Gridline platform.
Quickly and easily create and invest from a self-directed IRA with our integration to Equity Trust. You can both open and fund your account straight from the Gridline platform, either before investing or while creating your investment.
See a comprehensive list of all fund managers that Gridline is working with, including those previously listed for investing. This view allows you to explore the full catalog of opportunities, including managers who are only available in our Portfolio products or managers who may not be in the market currently but are likely to come back onto the platform with their next fundraiser.
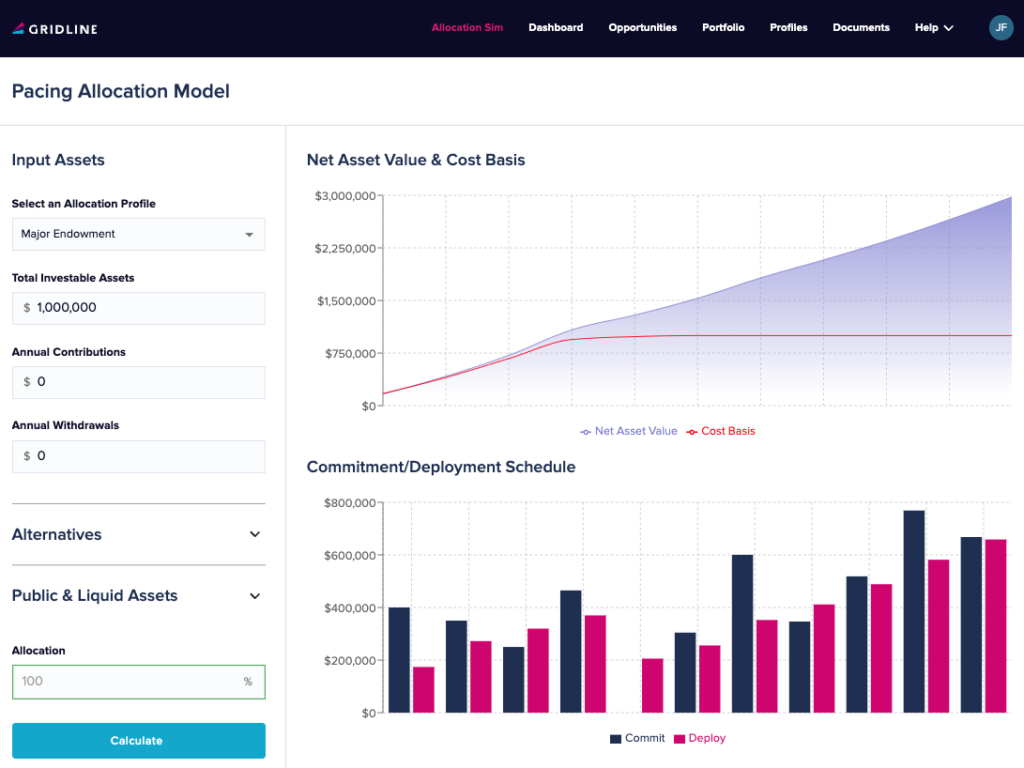
Understanding pacing and commitments across an entire portfolio can be challenging, but soon, you’ll be able to visualize commitments, cash flow, and projected portfolio growth with our new Allocation Simulator.
Gridline’s turnkey solution provides a range of features designed to simplify the launch and management of your own custom fund. From KYC to K-1, we provide a superior investing experience for you and your clients.
Book a time to speak with a member of our team to learn more, or sign up in minutes to gain access to the platform.
It’s the most wonderful time of the year. Lights are going up around town, kids are eagerly anticipating a break from the scholastic grind, and savvy investors are considering how to position their portfolios for maximum after-tax gains in the years to come. One popular strategy that has traditionally paired well with the festive season is tax-loss harvesting.
Tax-loss harvesting begins with an investor considering their likely tax bill for the year and noticing a higher number than they would like to see, perhaps from selling a big stock winner or business. Rather than foot a hefty tax bill today, investors can sell an investment that has declined in value and use the realized loss to reduce their taxes. This not only eases the temporary burden, but Vanguard estimates that it can improve after-tax returns by above 1% annually, with the largest benefits accruing to the largest taxpayers with net worths above $1.2MM.
To understand why that might be the case, consider an investor, Bob, who makes a $100 investment in a stock that declines in value to $80 over a year (a 20% loss) and subsequently doubles in value to $160 (a 100% gain) before he needs to sell it to retire. Were he to hold that investment to retirement, he would take home $148 net of an assumed 20% capital gains tax rate. If, instead, Bob sells the investment at a 20% loss in the first year, he can use that loss to offset ordinary income or other short-term gains taxed at an assumed 30% tax rate, saving $6 in taxes ($20*30%). If he then reinvests the $80 of proceeds and the $6 tax savings back into a similar investment, that investment could grow to $172 ($86*2) by Bob’s retirement. Even after paying taxes on his gains, Bob walks away with $154.80, or $6.80 more than he would have had holding the investment all the way to maturity. $2 of that is from the lower assumed tax rate, and $4.80 is from Bob’s ability to compound capital for a longer stretch of time before paying any taxes.
There are a couple of simplifications to Bob’s example for investors to consider. First, the difference in Bob’s tax rates between year one and retirement was 10%, which assumed that Bob had short-term capital gains or standard income to offset short-term capital losses. Standard income can only be offset to a maximum of $3,000 annually, though some losses can be rolled. Investors should consult tax professionals to understand the specifics of their situation. Additionally, Bob’s savings rely on the underlying asset’s volatility. Repeating the same exercise with a year-one value of $90 and an exit value of $130 yields only $3.07 of savings. Finally, if Bob sells shares in a stock and purchases shares in the same stock, he will run afoul of IRS rules around “wash sales” and lose his ability to deduct losses from his taxes. Wash sale rules prohibit investors from buying securities that are the same or substantially identical within 30 days of selling below cost, so for Bob to operate within the rules, he would need to either wait for over a month to reinvest and risk prices moving away from him, or invest in a substantially different security with potentially different returns. Investors should consult legal counsel for more specifics.
What does tax-loss harvesting have to do with alternative investments? Alternatives are a great place to park the cash from tax-loss harvesting because of high historic returns, most of those returns coming in the form of long-term capital gains, and no issues with wash sales. Data provider Hamilton Lane looked at 10-year rolling returns from Private Equity and public markets side-by-side and found Private Equity outperformed all three public benchmarks in all but a handful of quarters since 2001. On the private equity side, most of those returns have come from long-term capital gains because investments are typically held for three or more years. They also do not trigger wash trading rules, as each fund has a different mix of portfolio companies.
Tax-loss harvesting comes with some complexities investors should review carefully, but has been shown to increase after-tax returns and free up liquidity. Investors evaluating the strategy should consult tax and legal advisors and carefully consider which investments to rebalance into that steer clear of wash trading rules and provide compelling returns. Alternatives have a role to play in many accredited portfolios and deserve a long look from properly qualified investors.
Ready to diversify your portfolio with alternatives? Join our network of investors, wealth advisors, and family offices to get access to top-tier fund managers across venture capital, private equity, private credit, and real assets. Gridline is free to join. Get access now to review all fund details instantly.
Resources to Learn More: